T4 vs T4A vs T5: What Each Slip Reports and Who Gets One
The T4 vs T4A question comes down to the relationship behind the payment. A T4 reports employment income with CPP, EI, and tax withheld at source. A T4A reports pension income, self employment fees for services, scholarships, and other amounts that fall outside an employment relationship. A T5 reports investment income such as interest and dividends, and it comes from a bank or a corporation rather than an employer. All three are due by the last day of February, which for the 2026 tax year means March 1, 2027.
This guide covers who issues each slip, who receives one, and where the amounts land on your return.
What Is the Difference Between a T4, T4A, and T5?
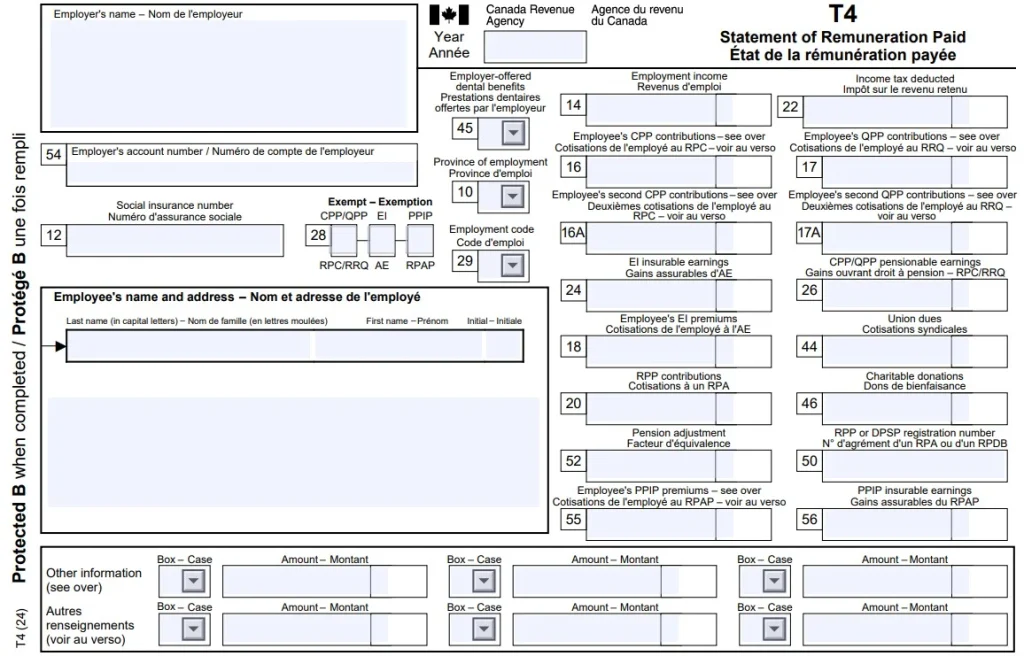
Each slip answers a different question about where money came from. The T4, officially the Statement of Remuneration Paid, covers people on payroll. The employer withholds income tax, CPP contributions, and EI premiums before the money reaches the employee, and the slip records both the gross pay and every deduction taken.
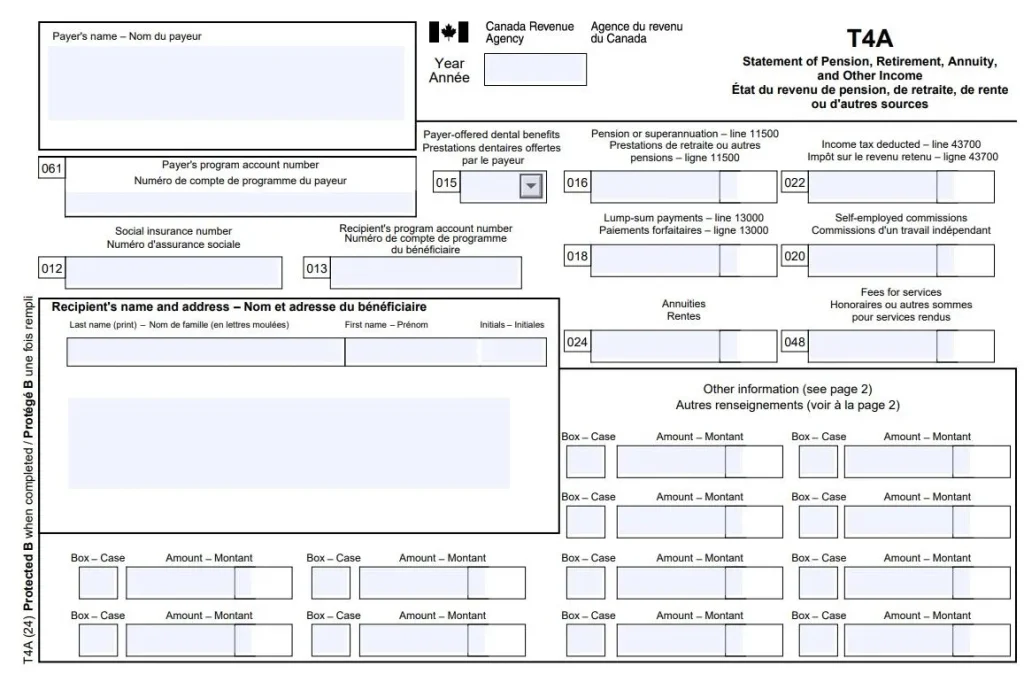
The T4A, the Statement of Pension, Retirement, Annuity, and Other Income, is the catch all of the three. It handles pension payments, annuities, lump sum amounts, scholarships, RESP income, and fees paid to someone working as a contractor. No CPP or EI appears on it, because none was withheld.
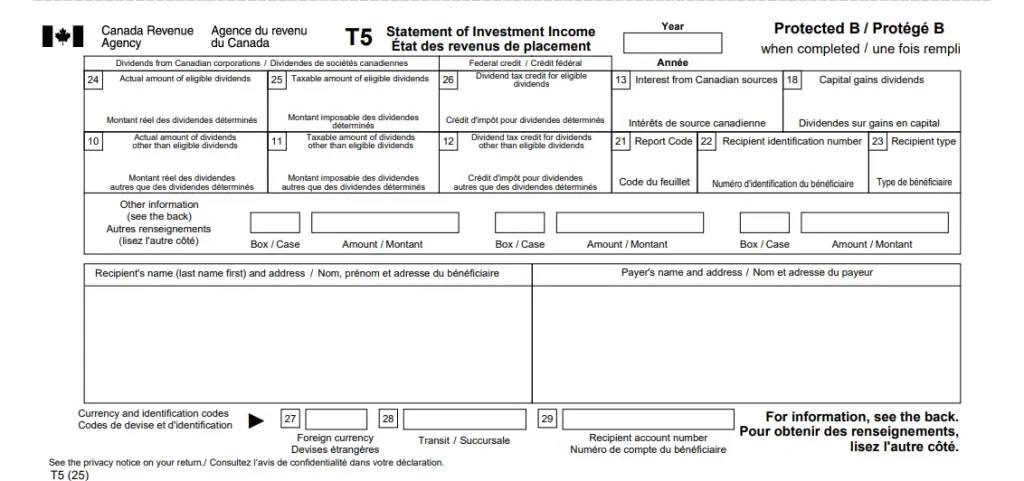
The T5, the Statement of Investment Income, has nothing to do with work at all. Banks issue them for interest, and corporations issue them for dividends paid to shareholders. The income was earned by capital rather than by labour, and that difference changes how it gets taxed.
T4 vs T4A vs T5 at a Glance
The table below sets out the three slips side by side.
| Feature | T4 | T4A | T5 |
|---|---|---|---|
| Official name | Statement of Remuneration Paid | Statement of Pension, Retirement, Annuity, and Other Income | Statement of Investment Income |
| Income type | Employment | Pension, contract fees, scholarships | Interest, dividends |
| Issued by | Employer | Payer, pension plan, school | Bank, corporation |
| CPP and EI withheld | Yes | No | No |
| Reporting threshold | $500, or any tax withheld | $500, or any tax withheld | $50 |
| Deadline | Last day of February | Last day of February | Last day of February |
| Main return line | 10100 | Varies by box | 12000 and 12100 |
Who Gets Each Slip?
The payment relationship decides which form the payer issues. Payroll produces a T4, contract and pension payments produce a T4A, and capital produces a T5.
Who Gets a T4?
Anyone on payroll receives a T4, including part year staff, seasonal workers, and directors paid for their role. The trigger is $500 of total pay in the calendar year, or any amount at all where income tax, CPP, or EI was deducted.
Box 14 holds employment income including taxable benefits, so a company vehicle or group life insurance premiums sit inside that figure rather than beside it. Our guide to payroll deductions in Canada explains which amounts feed which box, and employers who want the year end handled use payroll services in Mississauga.
Who Gets a T4A?
Contractors receive a T4A rather than a T4, with the payment reported in Box 048 as fees for services. Pension recipients get one for Box 016 amounts, students get one for scholarships in Box 105, and anyone drawing on an RESP sees the accumulated income in Box 040.
The threshold is $500 in a year, or any amount where tax was withheld. Businesses paying contractors need those totals tracked through the year rather than reconstructed in February, which is part of what bookkeeping in Toronto covers.
Who Gets a T5?
Shareholders receive a T5 for dividends, and savers receive one for interest. The threshold is only $50, so a modest savings account can trigger a slip, though banks often issue them below that amount anyway.
Owner managers see this slip every year once they pay themselves by dividend, since the corporation has to issue a T5 for every distribution. Our guide on how to prepare the T5 slip walks business owners through it, and we handle the corporate side through corporate tax return in Brampton.
Where Each Slip Goes on Your Tax Return?
T4 amounts are the simplest. Box 14 goes on line 10100 as employment income, and the tax in Box 22 feeds your total deductions. Several jobs in one year mean several slips, all added together, and our guide on how to report multiple T4 slips on line 10100 covers the arithmetic.
T4A amounts split by box, which is why the slip confuses people. Pension income in Box 016 goes to line 11500. Fees for services in Box 048 go on a T2125 as business income, where you deduct expenses against it. Scholarship amounts in Box 105 go to line 13010, often fully exempt for full time students.
T5 amounts split by type. Interest in Box 13 goes to line 12100 at full value. Dividends get grossed up first: eligible dividends rise by 38 percent and carry a federal credit of 15.0198 percent of the grossed up amount, while other than eligible dividends rise by 15 percent with a 9.0301 percent credit. Our guide to line 10100 on your tax return explains how these pieces assemble.
Common Mix Ups Between T4 and T4A
Contractor classification causes the most damage. A business issues a T4A to someone it treats as a contractor, CRA reviews the arrangement, and the worker gets reclassified as an employee. The employer then owes both halves of the CPP and EI that should have been withheld, plus interest, and the employee half cannot be recovered from someone who left months ago.
The test looks at control over how the work gets done, who owns the tools, the chance of profit or loss, and how integrated the person is into the business. A contract calling someone a contractor carries no weight on its own. Businesses with recurring contractor relationships should settle this before year end, not during a review.
The second mix up involves Box 048. Fees for services exclude GST and HST, so a contractor billing $10,000 plus HST appears on the slip at $10,000. Many payers report the full invoice amount and overstate the contractor’s income. Our guide to small business tax in Canada covers the reporting side for owners handling this themselves.
Match the Slip to the Relationship
The T4 vs T4A vs T5 choice is never about preference. The nature of the payment decides the form, and issuing the wrong one creates problems for both sides of the transaction.
Employers should review every payment category before February: payroll goes on T4s, contractor fees and pension amounts on T4As, dividends and interest on T5s. Recipients should check that each slip matches what they actually received, since an error found in February is far cheaper to fix than one found during a CRA review. The filing date for all three is the same, and our guide to the T4 filing deadline for employers covers the penalties for missing it.
Tax Return Filers PC prepares year end slips for businesses and reconciles them against the returns they feed, including personal income tax in Calgary for owners reporting several slip types at once.
FAQs
Book a Free Meeting with Our Tax Experts
Take the first step toward better tax planning with a free consultation. Our team is ready to review your situation and provide clear guidance. Book a time slot directly on our calendar and we will connect with you shortly.